

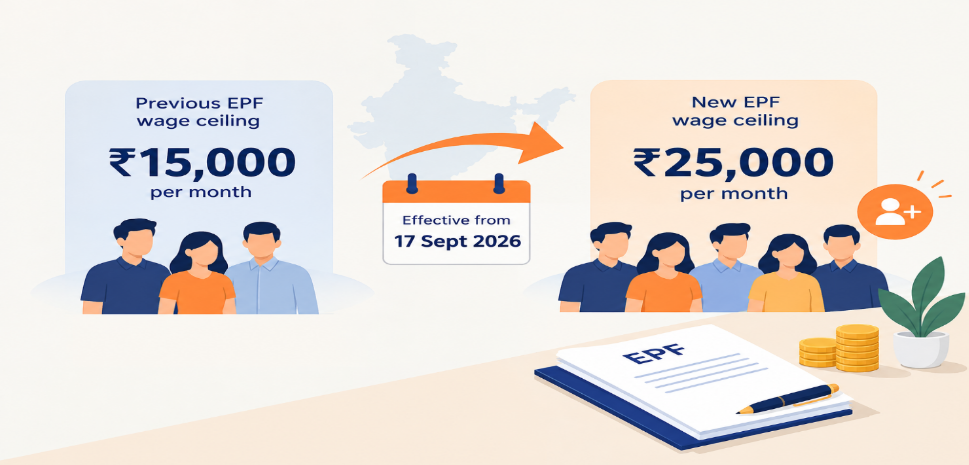
India increased the EPF wage ceiling for mandatory coverage from INR 15,000 to INR 25,000 per month. The Union Cabinet approved the change on 16 September 2026, with the revised ceiling taking effect from 17 September 2026. Foreign businesses employing people in India should identify potentially affected employees, review EPF wage calculations and assess whether payroll systems and contribution practices need to be updated.
On 16th September 2026, the Union Cabinet approved a change that will alter payroll calculations for lakhs of employees in India. The statutory wage ceiling for mandatory Employees’ Provident Fund (EPF) coverage has shifted from INR 15,000 to INR 25,000 per month. A press release from the Ministry of Labour and Employment confirmed that the revised EPF new rule effective date is 17th September 2026. The Government has stated that the change is expected to bring more than 51 lakhs additional employees within the mandatory EPFO coverage. The previous INR 15,000 ceiling has stood untouched since September 2014 when it was last revised upward from INR 6,500, making it a significant revision in a decade.
For any foreign company employing people in India, this is not just a headline to skim past. The EPF new rule changes who must be enrolled in India’s principal social security net and reopens payroll assumptions that many overseas HR and finance teams-built years ago. It touched employee eligibility, contribution calculations, payroll configurations and cost of running an Indian workforce. It is advised to get in touch with professional regulatory advisory service to understand the intricacies revolving around it. But before that, let’s look briefly about what has actually changed and its impact on the businesses.
What Has Changed as Per EPFO New Update
The Provident Fund wage ceiling is the monthly limit used to determine mandatory EPFO coverage. It is not same thing as gross salary, basic pay or cost to company.
| Particular | Position until 16 September 2026 | Position from 17 September 2026 |
|---|---|---|
| EPFO wage ceiling | INR 15,000 per month | INR 25,000 per month |
| Ceiling last revised | September 2014 | September 2026 |
| Additional employees expected under mandatory coverage | — | More than 51 lakh |
The cabinet’s announcement raises the ceiling of the doorway through which employees enter mandatory EPF, EPS, and EDLU protection. However, it does not by itself, restate how contributions are calculated once the employee is inside that doorway. The Ministry of Labour and Employment and EPFO are now expected to carry out the statutory and administrative steps needed to implement it. This includes circulars, portal updates and scheme instructions.
Which Employees Are Affected by The Revised EPF Ceiling
The employees that are directly affected by this change are those whose EPF-relevant wages sit between INR 15,000 and INR 25,000 a month and who were previously outside mandatory coverage, purely because of old ceiling. Indian payroll law works with a defined concept of wages. An employee drawing INR 24,000 in gross monthly pay cannot be assessed correctly until the employer has isolated the components that count as EPF wages under the applicable rules.
There is also a distinction worth holding onto between employees already inside the EPF system and those who will qualify newly. An employee who became a member years ago when their wages were below the earlier ceiling remains the member. The revised threshold may impact both new hires and certain categories of existing employees, depending on EPFO implementation guidance and the employee’s membership status.
How Does the Change Affect Foreign Employers in India
A foreign parent designing an Indian salary structure often starts from a home-country template and assume the components will translate neatly. The employees most affected by this change sit in the INR 15,000 to INR 25,000 wage band, a group that previously fell outside mandatory coverage purely because of where the ceiling was fixed.
For employers the impact comes down to three areas. First, they need to identify which employees are covered based on the wages considered under EPF rules. Second, they need to check whether the contributions are being calculated on the statutory ceiling or on a high-wage amount. And finally, the employee’s own contribution may also change, which can affect their monthly take home pay while increasing their EPF savings. These EPF rules for employers 2026 also make EPF compliance for foreign companies in India an important part of reviewing Indian payroll arrangements.
How Could the Change Affect Payroll Contribution
A change in the EPF wage ceiling can affect payroll in more than one way. An employer needs to look separately at the employee’s contribution, the employer’s contribution and the overall cost of employment. The EPF contribution after wage ceiling increases will depend on the wage base applicable to the employee and the contribution practice followed. The employee contributions are calculated at 12 % of the applicable wages. The employer’s contribution is divided between the relevant EPFO scheme as prescribed under the rules. The change in the ceiling can be shown through a simple illustration:
| Basis | Calculation | Monthly employee contribution |
|---|---|---|
| Earlier ceiling | 12% of INR 15,000 | INR 1,800 |
| Revised ceiling | 12% of INR 25,000 | INR 3,000 |
This is illustrative only. These figures only show what the contribution would be if 12% was applied to the full ceiling. They should not be treated as the actual contribution for every employee. The actual figure depends on the wage base applicable to that employee, their membership history and the operational instruction EPFO issues as implementation proceeds. An employer who already contributed on actual wages above the old ceiling, rather than capping contributions at INR 15,000, may see a smaller shift than one whose payroll was built strictly around the earlier limit.
How is the EPF Change Different from the PMVBRY Incentive
The increase in the EPF wage ceiling is separate from the Pradhan Mantri Viksit Bharat Rojgar Yojna (PMVBRY). The scheme approved by the Union Cabinet in July 2025, provides eligible employers with financial support for additional employees who meet the scheme conditions. The support can be up to INR 3000 per month for an eligible additional employee, with longer support available qualifying manufacturing establishments.
PMVBRY has its own eligibility requirements, including conditions relating to additional hiring, employee retention and regular filing of Electronic Challan cum Return (ECR).
For a foreign business employing people in India, EPF and PMVBRY should be assessed separately. The revised EPF ceiling affects statutory coverage and payroll calculations. PMVBRY is a separate employment incentive that an eligible employer may be able to claim.
What Should Foreign Businesses Review in Their Indian Payroll
For a foreign business with presence in India, it is important to understand how the revised ceiling affects its existing payroll structure. A structured payroll compliance for foreign companies in India review can cover the following points:
- Identify employees whose statutory wages fall between INR 15,000 and INR 25,000.
- Confirm the applicable wage components considered for EPF purposes under prevailing EPF laws and judicial guidance.
- Check whether current contributions are calculated on the ceiling or on actual eligible wages.
- Calculate the potential change in both employer and employee contributions for affected employees.
- Update payroll systems and relevant salary or compensation records once the applicable requirements are confirmed.
- Ensure relevant UAN, Aadhaar and KYC details of the employee are properly maintained, where required.
- Keep track of further notifications, circulars and implementation instructions before making system-wide changes.
Conclusion
The move from INR 15,000 to INR 25,000 is the significant change to India’s EPFO wage ceiling in more than a decade. The new EPF new rules reflects a deliberate policy choice to keep statutory social security coverage aligned with rising wages. For a foreign business employing, or about to start employing people in India, the practical task is not just noting down the numbers. It is working out whether that number changes anything at all.
Businesses that treat this as an opportunity to tidy up their payroll assumptions tend to fare better when the next round of implementation guidance arrives. Given that many of the details still depend on the upcoming circulars related to EPFO and scheme amendments, it is worth having the calculations done properly rather than working on an estimated number. For a clear, employee specific view of how the revised EPFO threshold applies to your Indian payroll, get in touch with professionals at Stratrich.
Frequently Asked Questions (FAQs)
The Union Cabinet approved raising the EPFO wage ceiling for mandatory coverage from INR 15,000 to INR 25,000 per month on 16th September 2026. It officially took effect on 17th September 2026. The change is expected to bring more than 51 lakh additional employees within the mandatory EPFO coverage.
No, not necessarily. The revised figure is a coverage threshold, not a fixed contribution base applied uniformly. Whether it affects a given employee depends on their applicable EPF wages, their existing membership status and the contribution practice their employer already follows.
Employees whose EPF-relevant wages fall between INR 15,000 and INR 25,000 a month are most likely to be affected by the update. It is important to keep in mind that gross salary alone is not a reliable way to identify the group, since Indian payroll uses a specific, defined concept of wages for EPF purposes.
No. PMVBRY is a separate Employment Linked Incentive Scheme, approved by the Cabinet on 1 July 2025. It offers eligible employers up to INR 3,000 per month per additional employee retained for at least six months. It depends on conditions such as minimum additional hiring and establishment size. It should be assessed independently rather than assumed to cover any rise in EPF contribution.
Not necessarily in every case. The impact depends on the applicable wage base, the employee’s membership history and whether the employer currently calculates contributions on the statutory ceiling or on actual eligible wage. The revised ceiling may therefore have different cost implications for different employers.
A foreign company should identify employees that are affected by the revised ceiling using the correct EPF wage definition. They should look into how the contributions are currently calculated, update salary template and costs models where needed, and keep track of EPFO circulars as the implementation details are issued. Considering several aspects are still pending formal guidance, it is wise to have payroll calculations verified against the latest rules before finalising any changes.
For a foreign company operating in India, EPF applies to the establishment itself once it’s crossed the prescribed employee threshold. EPF coverage works once the establishment is registered under the EPF Act. The scheme covers Indian employees by default, while foreign nationals on assignment are generally brought in as international workers. Applicability for each employee category must be confirmed individually as these provisions can be affected by bilateral social security agreements.
CTC is not a statutory concept for PF, so it has no say in an employer’s liability. Contributions are worked out on wages as defined under the applicable provisions. CTC is simply the total cost an employer incurs for an employee, and it reflects whatever the two parties have agreed. Where contributions were earlier paid on the INR 15,000 wage ceiling despite higher actual PF wages, the higher ceiling will push up EPF, EPS, EDLI and admin charges. Employers can also see their share of these contributions as part of good HR practice, since it supports employee satisfaction and retention.
CTC plays no statutory role in deciding the employer’s liability. That comes from the statutory definition of wages and the relevant provisions.
So, the employer’s contribution cannot be turned into an employee deduction just by calling it part of CTC. Employers should make sure statutory contributions are paid correctly and that employees’ statutory wages are not reduced contrary to applicable law.
The change is more of a shift than a reduction. Money moves from the employee’s take-home pocket to the PF account pocket. It is still the employee’s own money, and the employer matches any increase in the employee’s EPF share. The one exception is the EPS contribution, which is set aside to provide pension later.
In exchange, the employee builds safe, compounding savings that earn better interest and carry tax benefits, along with a guaranteed pension and free insurance cover. The funds also stay accessible, with up to 75% of the balance withdrawable at any time for any need.
No. The Government’s share towards EPS is unchanged and remains restricted to 1.16% of the first INR 15,000 of monthly wages. Raising the statutory ceiling to INR 25,000 does not, by itself, take the Government’s contribution past INR 174 per month per member. The member’s pension is not affected either, as it depends on pensionable wages and pensionable service.
EPF contributions will vary with the employee’s applicable PF wages after the change from October wage onwards. The illustration below shows employee and employer contributions at different wage levels:
| Monthly PF wages | Employee EPF contribution (12%) | Employer EPS contribution (8.33%) | Employer EPF contribution (3.67%) | EDLI contribution (0.5%) | EPF administrative charges (0.5%) |
| INR 10,000 | INR 1,200 | INR 833 | INR 367 | INR 50 | INR 50 |
| INR 15,000 | INR 1,800 | INR 1,250 | INR 550 | INR 75 | INR 75 |
| INR 20,000 | INR 2,400 | INR 1,666 | INR 734 | INR 100 | INR 100 |
| INR 25,000 | INR 3,000 | INR 2,083 | INR 917 | INR 125 | INR 125 |
| INR 35,000 | INR 3,000 | INR 0* | INR 3,000 | INR 125 | INR 125 |
*EPS membership is open only to employees whose wages, at the time of joining or on the date the revised wage ceiling comes into effect, do not exceed INR 25,000 per month.
The INR 35,000 example reflects the statutory contribution limit. The employee contribution is capped at INR 3,000. The employer contribution is also INR 3,000, all of it going to EPF since EPS does not apply.
The minimum EPF administrative charge is INR 500 per month for an establishment with at least one contributing member. If there are no active contributing members in a wage month, the minimum charge is INR 75 per month per establishment.
Employees in this wage band can now contribute on wages up to INR 25,000, and the employer contribution rises to match. For an employee drawing INR 20,000, the employer contribution goes from INR 1,800 to INR 2,400 per month, which builds a larger EPF balance. The higher ceiling also lifts the pensionable salary considered at retirement, and that increases the pension payable under EPS.
The higher wage ceiling is not expected to create a separate burden for MSMEs. They contribute at the same rate as any other establishment under the Code on Social Security, 2020. The added cost from the higher ceiling can be partly offset by the incentive of up to INR 3,000 per month for every additional employment created under PMVBRY.